
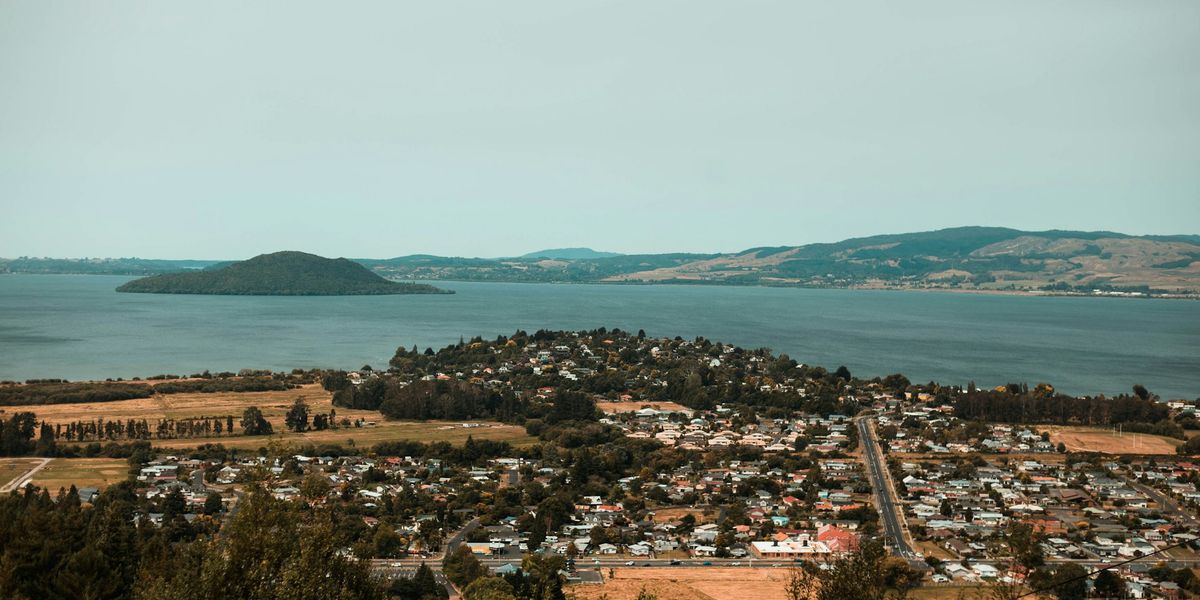
Rotorua is one of New Zealand's most recognisable destinations, and tourism is the first thing most people think of. Geothermal parks, Māori cultural experiences, the lakes and some of the country's best mountain biking bring visitors year-round. But the district's economy runs deeper than that. Forestry and wood processing, farming, construction and a busy retail and service sector all play a big part. fundU offers business loans in Rotorua from $20,000 to $1m, secured on property, with decisions made by our own credit team.
We lend against property in Rotorua and right across the Bay of Plenty, from Ngongotahā, Lynmore and Owhata to the lake communities, Mamaku, Reporoa and the surrounding rural districts. Our central lending team handles everything by phone and online, so there's no need to visit an office.
What shapes Rotorua's business economy?
Tourism has been through a rollercoaster in recent years. Border closures emptied the city of international visitors, then the recovery brought them back unevenly. At the same time, many Fenton Street motels were used for emergency housing. As those properties return to the visitor market, their owners face refurbishment bills and the job of rebuilding bookings.
The other big pillar is forestry. Rotorua sits in the heart of the central North Island's plantation forests, and harvesting crews, trucking firms, sawmills and wood processors are major local employers. Their cash flow tends to follow log prices, export demand and harvest volumes, and a weak patch can arrive with little warning.
Farming, from dairy on the Mamaku Plateau and around Reporoa to drystock in the hills, adds a third rhythm. So does steady demand for builders and trades as the city grows.
Rotorua's visitor year has its own pattern too. Domestic visitors fill the city during school holidays and long weekends, events and mountain biking bring crowds through the warmer months, and international travellers peak over the summer. Midweek winter trade can be thin. For many hospitality and accommodation owners, the challenge isn't the year's total income. It's getting through the quiet weeks with enough left to invest before the next busy stretch. Our guide to seasonal business cash flow has practical ideas for managing the swings.
Tourism and forestry businesses can both have lumpy income. Interest-only or capitalised interest terms, where there are no scheduled monthly repayments during the term, can keep a loan manageable through the quiet stretches.
Which Rotorua businesses do we work with?
- Motels, lodges and holiday accommodation along Fenton Street, around the lakefront and in the wider district.
- Tourism and activity operators, from cultural and geothermal experiences to lake cruises, fishing guides and bike shops near the Whakarewarewa Forest trails.
- Cafés, restaurants and bars in the CBD, along Eat Streat and in the suburbs.
- Forestry contractors, log truck operators, sawmills and wood processors across the district.
- Builders, trades and engineering businesses serving local housing, commercial work and industry.
- Farmers and rural service businesses around Mamaku, Reporoa and the surrounding plateau.
Our hospitality and tourism page covers the funding challenges these businesses face in more detail.
What property can be used as security in Rotorua?
We consider a wide range of property in the district:
- Homes and rentals in Rotorua's suburbs and the lake communities
- Holiday homes around Rotoiti, Ōkāreka and Tarawera
- Motel and accommodation properties, case by case
- Commercial and industrial property in the CBD and the district's industrial areas
- Lifestyle blocks and some rural property, case by case
- Property owned by your company, family trust or a supporting family member
Geothermal ground conditions are a feature of some Rotorua properties, and a registered valuer will take them into account. They don't automatically rule a property out.
If your home already has a bank loan, a second mortgage can use its equity without disturbing your bank. For accommodation or commercial buildings, our commercial property loans page explains how we lend against them.
What do Rotorua owners use fundU loans for?
| Rotorua situation | How fundU can help |
|---|---|
| Motel returning to the visitor market needing refurbishment | Fund the upgrades, repaid from improved trading or a refinance |
| Forestry contractor facing machinery repairs during a slow patch | Property-secured funding for gear, fuel and wages |
| Tourism operator after a quiet winter | Cover costs until the summer and holiday peaks |
| Customers paying late | Working capital while debtors catch up |
| GST or PAYE arrears | Pay Inland Revenue out and stop penalties and interest |
| Past credit problems or a bank decline | A decision based on the property, the purpose and the exit |
If slow payers are the problem, our guide to late-paying customers and cash flow has practical steps. And if your credit history is holding you back, our bad credit business loans page explains how we look at it.
Example scenario
The owners of a leasehold motel business on Fenton Street had come through a period when most of their units were contracted for emergency housing. When that arrangement ended, the rooms needed new carpets, bathrooms and furniture before they could compete for tourists again, and the bank declined to fund it on the back of recent trading. The owners had a home in Lynmore with a bank mortgage and good equity. We lent $240,000 by second mortgage on capitalised interest terms, so there were no monthly repayments while the refurbishment was completed and bookings rebuilt. The exit was either a refinance with their bank or the sale of the motel business once a full year of tourist trading was on the books.
How do I apply from Rotorua?
- Enquire online or call 09 875 4577. It takes a couple of minutes and doesn't affect your credit score.
- A lending specialist gets in touch to understand the purpose, the property and how you'll repay.
- Indicative terms are outlined if the loan is a good fit.
- A registered valuer inspects the property and our credit team makes the decision.
- Your lawyer signs off the documents and we settle. Once approved, funding can happen in as little as 24 hours in some cases.
Not sure what we'll look at? Our business loan checklist covers it.
Whether you run a motel on Fenton Street, a crew in the forest or a café on Eat Streat, good Rotorua businesses deserve a fair go. See if you qualify and we'll be in touch.
Frequently asked questions
Can a Rotorua motel owner borrow to refurbish units?
Yes. Motel and accommodation owners often need funds to refurbish rooms, upgrade bathrooms and kitchens or refresh signage and grounds. We can lend against the accommodation property case by case, or against your home or other property, with repayment from improved trading, a refinance or a sale.
Do you lend to forestry contractors in the Rotorua area?
Yes. Forestry and wood processing businesses often need funds for machinery, repairs, fuel and wages, especially when log prices or harvest volumes dip. A loan secured on your home or other property can fund those costs, with repayment from contract income, a refinance or an asset sale.
Do you lend around the Rotorua lakes and rural areas?
Yes. We lend against property in Rotorua and right across the district, including Ngongotahā, Lynmore, Owhata, the lake communities of Rotoiti, Ōkāreka and Tarawera, and rural areas such as Mamaku and Reporoa. Lifestyle and rural property is considered case by case.
Can I get a business loan if my Rotorua business has IRD debt?
Yes, IRD debt doesn't rule you out. Paying out Inland Revenue is one of the most common reasons owners contact us. A property-secured loan can clear GST, PAYE or income tax arrears in one go, stop penalties and interest building, and give you a single plan to repay.
A practical next step
Ready to see what's possible?
Tell us what the business needs, when you need it and what property is available. A fundU lending specialist will call you back to talk it through — enquiring is free and won't affect your credit score.